• Blog
  • About
Powered by Blogger.

Path to prosperity

The airline industry has been one of the most badly hit by the Covid-19 pandemic as international air travel ground to a halt. Even as there are green shoots of recovery in the economy and green lanes are opening up, air travel is still >90% down from pre-Covid levels. In light of this, investors have been reconsidering their stakes in the industry. I recently read an article about the recovery in the airline industry being unequal and would like to give my take on the points mentioned. Generally, it argued that the characteristics of low-cost carriers ('LCCs') would allow it to recover faster than full-service carriers. 

1. LCCs serve point-to-point destinations

Direct flights reduce the number of points of contact during travel and could give passengers greater peace of mind when travelling. We have seen pictures and videos circulating around of passengers in full PPE suits in airports and this further highlights the concerns passengers have about being locked up with strangers in a flying metal box for a few hours. LCC typically serve direct flights vs full-service carriers like SIA, which operate more of a hub and spoke model. 
Passengers at Changi Airport ready with PPE

2. LCCs operate regional flights 

Operating regional flights could be a plus in this case as passengers would want to reduce the time spent in an aeroplane. Such flights are closer and are within the tolerable risk perception of travellers. Additionally, the recession brought about by Covid-19 could lead households to tighten purse strings and opt for regional destinations. LCCs that operate in countries with domestic travel should start to see shoots of recovery with governments pushing hard to boost domestic tourism. 

3. LCCs serve leisure travellers

The profile of passengers for LCCs tends to be leisure travellers as their price-sensitive nature is met with competitive prices from LCCs. On this front, I'm not sure if this is positive or negative for LCCs. On one hand, corporate travel is likely to be cut back with weakening profitability whereas leisure travel is always likely to be around due to an intrinsic nature to explore new places. On the flip side, corporate travel is many times more likely to be classified as 'essential travel' that can restart sooner. 

Additional points of consideration would be survivability. Full-service carriers with strong backing from governments should have much better support during these times and are less likely to fall into financial ruin. This is evidenced by SIA's S$8.8bn rights issue supported by Temasek. The longer the pandemic drags on, the less likely non-government-backed LCCs can survive. 
Share
Tweet
Pin
Share
No comments

As the world experiences an uneven recovery from the Covid-19 virus, investors continued to pile into markets driving the S&P and NASDAQ indices to all-time highs. The divergence between reality and stock markets have been explained by some as the lack of any viable alternatives for return as interest rates have plummeted. 

On the S-REITs front, industrial REITs have continued their outperformance while hospitality and retail continue to lag. In this article, I will explore some general concerns investors have regarding REITs in order to provide readers with more tools to evaluate REITs. 

1. Have equity valuations fully accounted for real estate valuations?

In my opinion, the short answer is 'No' as most valuations would have been done at the last year-end, generally being Dec 2019. In Dec 2019, Covid-19 was still in its nascent stages and valuers were unlikely to have factored in the profound changes that the pandemic has brought about. As cashflow and growth are inputs of certain valuation methods, I think the decline in both would lead to lower valuations when assets get revalued soon. 

An example of this valuation decline from book value would be OUE Limited's sale of US Bank Tower for US$430m vs its book value of US$650m (~1/3 lower!). Additionally, I do believe that asset owners are holding back on conducting asset revaluations as this could have a negative impact on loan covenants (Ie. fall in asset value leading to higher LTVs). 

2. Could leverage limits be breached?

Leading on from my previous point, this is certainly true as valuations decline. The key concern about breaching leverage limits would be the implications on capital structure. If a REIT is close to breaching the limits, it is more likely to embark on equity fundraising (possibly dilutive). This could be why we are seeing smaller premiums (or larger discounts) attributed to REITs with >40% gearing like ESR REIT and ARA Logos Trust. From a pure property investment standpoint, a 40% LTV is not actually something to be very worried about as private funds do not have such limits and tend to go over 50% LTV. However, being a REIT comes with this trade-off of extra regulations. 

For investors with a longer memory, S-REITs undertook extremely dilutive equity fundraisings during the GFC period headlined by blue-chip names like Mapletree Logistics Trust and Capitaland Commercial Trust. That exercise caused a crash in REIT stock prices; the crash was a short-term one and REITs subsequently had a strong run until 2019. 

3. When will things go back to normal?

Due to the difficulty in quickly testing for Covid-19, I believe that a return to the old norm will come only when a fast test and a vaccine are found. As earlier mentioned, different REIT subsectors have had different impacts from Covid-19. Subsectors like data centres and logistics are strong beneficiaries from the shift to a virtual economy and stay-at-home nature that comes with Covid-19. Others like hotels have been decimated while the future of retail and office are still up in the air. 

For both office and retail, I believe that the longer the pandemic lasts, the more people would be accustomed to flexible working and online shopping respectively. Covid-19 has accelerated nascent trends and this may not be reversible. On the flip side, we have also been seeing office workers pining to return to office as work-from-home arrangements have caused additional stress. Shoppers have also been craving the full sensory engagement that comes with seeing and touching items. 

As for hospitality, while it is a short term mega loser, I do think that in the long run, it will recover more than office and retail, especially leisure travel. Corporate travel could be somewhat hampered by greater adoption of virtual conferencing but leisure travel is something I believe society is itching to go back to. Of the top 5 oldest business that have been around since before 1300, 4 of them are hotels. This further emphasizes the intrinsic need that humans have for exploration and discovery. 

Conclusion

While the market continues to power on, I do think that the Covid-19 situation has shown the importance of having a strong balance sheet and survivability. These are characteristics that are present in most REITs as they have strict gearing limits and have cashflows backed by assets.  When the time comes, I believe REITs will come back in favour. 
Share
Tweet
Pin
Share
No comments

PropNex released its 1H20 financial results and reported a 151% surge in net profit after tax to $16.0m. According to PropNex the key driver of earnings growth was the project marketing services segment, which had revenue growth of $75.1m vs total revenue growth of $75.2m. As this is a higher margin segment relative to the resale market, there was an increase in gross profit margin to 11.4% in 1H20 vs 9.8% in 1H19. 

PropNex 1H20 Results (Source: PropNex)

In previous quarters, PropNex mentioned that transactions usually would have a 1-2 quarter delay from the time the agreements are signed until the time PropNex is actually able to recognize revenue. Hence, we can deduce that the strong showing in 1H20 can be attributed to the stronger 2H19 in property sales. 

Due to Covid-19 and the ensuing Circuit Breaker in Singapore, 2Q20 sales volume was strongly affected as there was a 37.6% qoq decline in private residential properties sold from 4,269 to 2,664. I believe that this would negatively impact 3Q and 4Q results and do not rule out a >20% decline in net profit in the coming quarters. 

Outlook

PropNex believes that despite the headwinds brought about by weaker economic growth, demand in the property market can continue to be resilient due to a few factors
  1. Lower interest rates to reduce the cost of buying properties with a mortgage
  2. Developers adjusting their prices to more competitive levels
  3. The weaker economic environment could help keep prices stable
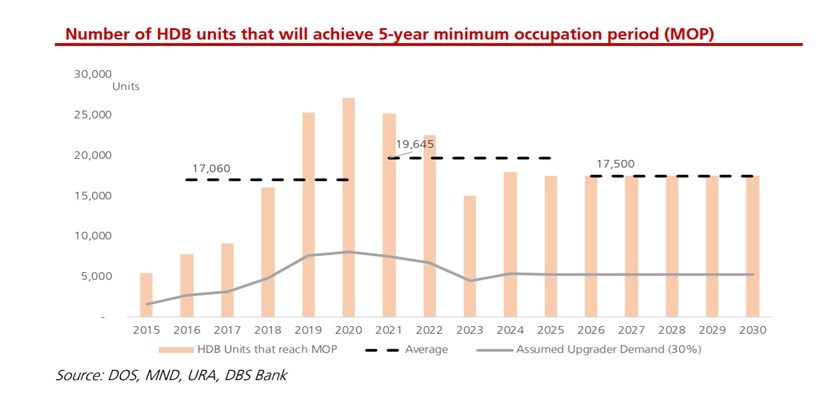
PropNex also estimates that there could be 8,000-8,5000 new home sales in 2020 with a total of 14,500-15,500 total units (including resale) vs 19,150 in 2019. On the HDB front, PropNex forecasts HDB resale volume to be between 20,000 to 22,000 for FY20 vs 23,714 in 2019. The softer decline in HDB volumes reflects the relative affordability of public housing and also the large chunk of flats reaching their MOP in 2019/2020. 

Takeaways

While I agree that lower interest rates make it conducive for buyers, it also increases the holding power of sellers who may not have adjusted down their selling price expectations. Therefore, transaction volumes may continue to remain low. The generous support provided by the government to businesses and individuals also helps to alleviate some of the financial pressures facing homeowners, in turn, lowering any urgent need for liquidity. 'Desperate' sellers could be HDB upgraders who have to sell their property. 

On the topic of HDB upgraders, it was initially expected that 2020 would see a bumper crop of them due to the large number of HDB flats reaching their 5-year MOP. However, in light of the pandemic and uncertainties, I believe that a number of upgraders could have held back their upgrading plans until their job outlook becomes more certain. Assuming timelines are pushed back by 1 year, this could also result in 2021 having a super crop of 5-7 year-old HDBs being on the resale market. With completions of the latest BTO launch expected to be in 2025-2027, anxious homebuyers could turn to the resale market instead. 

Another area to look out for is potential fire sales from developers racing to beat the ABSD deadline. In Jun 2020, we saw an instance of this (https://www.businesstimes.com.sg/real-estate/to-beat-absd-38-jervois-developer-launches-fire-sale-to-clear-units) when the developer of 38 Jervois slashed prices by up to $500,000 (13-24% discount) to avoid the ABSD. Unless absolutely necessary I believe that developers will try to hold on to their prices as major price cuts could result in options not being exercised, angry buyers who bought earlier or even impairments. 
Share
Tweet
Pin
Share
No comments

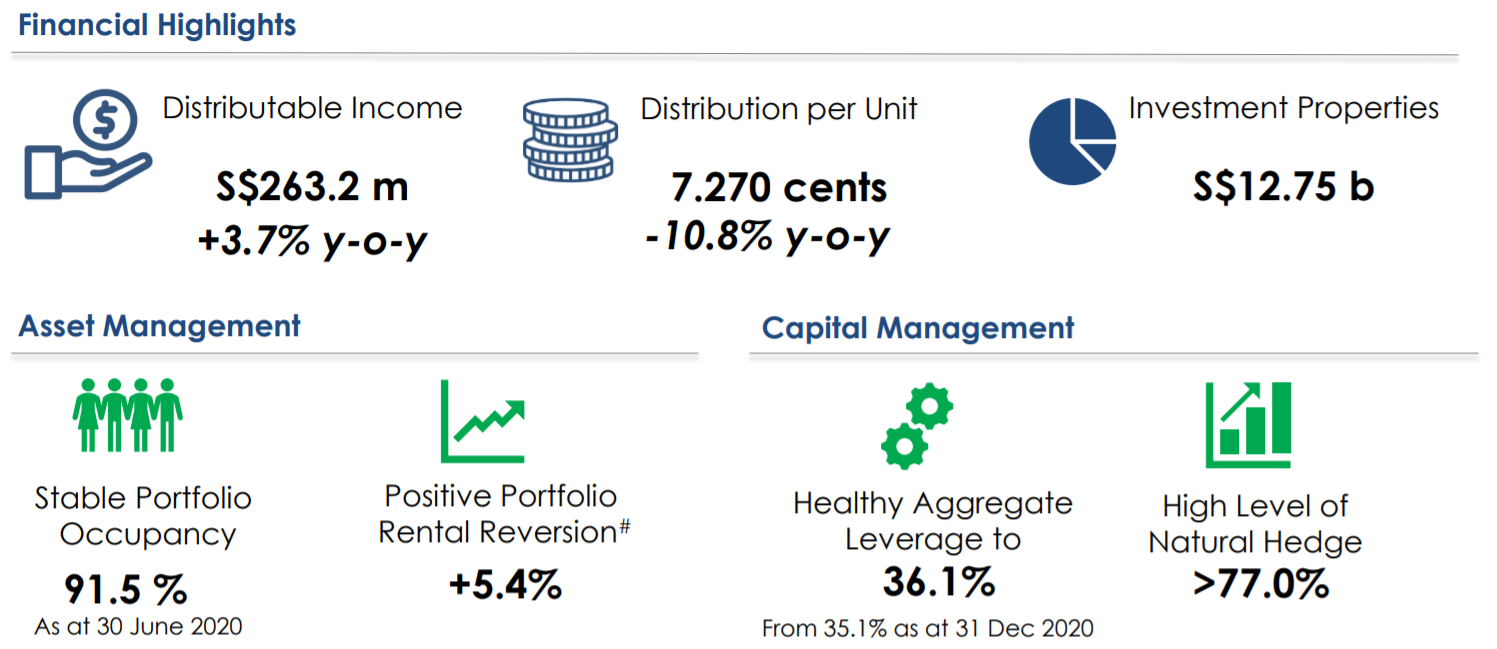
Ascendas REIT announced their results about 2 weeks ago and reported a 3.7% growth in distributable income but a 10.8% yoy decline in 1H20 DPU. Broadly speaking results were seen as positive despite the Covid-19 pandemic raging on in other sectors. Positive rental reversions, especially in business parks, were encouraging and gearing of 36.1% continues to provide AREIT with a healthy debt headroom for acquisitions. In this article, I would like to focus on key points brought up during the analyst briefing that investors may have missed if they merely looked at the announcements on SGX.

AREIT 1H20 results highlights (Source: AREIT)

1. Positive reversions in the face of weakening outlook not weird at all

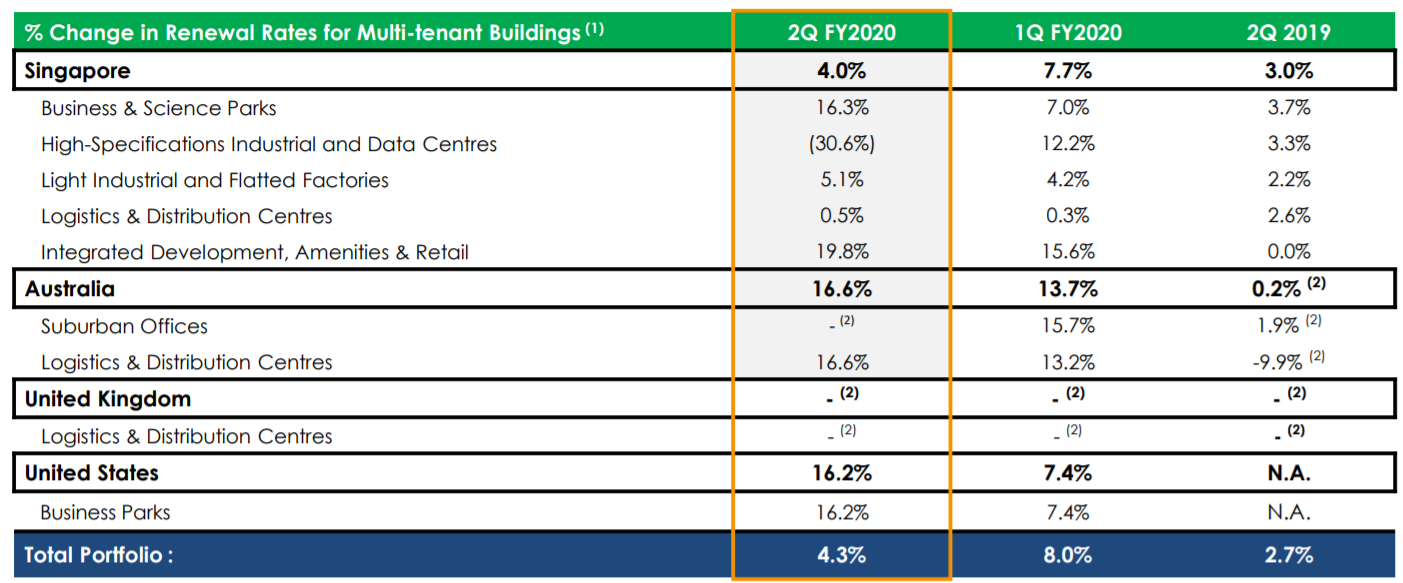
At first glance, it seems weird that AREIT could report +4.0% positive rental reversions in Singapore and +4.3% for the total portfolio despite the weakening outlook. However, management has revealed that a number of these discussions had already started taking place before Covid-19 hit and that properties were also under-rented relative to market. The positive reversions represent a mark-to-market of expiring rents rather than an actual growth in market rents. 

In particular, the management highlighted business parks as a bright spot with multiple instances of 20%+ reversions. The specific example given was that of an international bank renewing its lease at Changi Business Park for >20% reversion on a new 3-year lease for the same space (no reduction or expansion in space). CEO also highlighted that this was a positive read-through for the business park segment. 

For the rest of FY20, the management has guided for mildly positive rental reversions but cautioned that this was not indicative of the direction that the market was moving in. A better gauge could be looking at occupancies instead. 

AREIT rental reversions (Source: AREIT)

2. Logistics demand more transient in nature

Much has been said of the new-found stability and strength of logistics tenants that support e-commerce and Covid-19 related stockpiling. However, during the analyst briefing, AREIT did not believe that those 2 would drive the logistics sector much higher. 

Firstly, Covid-19 related stockpiling appears to be done on leases <1 year. Therefore, should the pandemic subside, landlords could see a decline in demand for such spaces. In the short term, we can probably see an improvement in rents from such short leases as they tend to be higher than leases with longer commitments. Such short leases also did not really have an impact on rental reversions as reversions only account for renewal leases >12 months. 

Next, while e-commerce has been doing well, it does not make up the bulk of leasing demand for logistics spaces. Instead, AREIT CEO mentioned multiple times that logistics demand in Singapore is driven by contract manufacturing and ~80% of it serves international markets. Therefore, the key catalyst for logistics would be whether Singapore can continue to attract contract manufacturers here and if product demand remains at current levels. 

Generally, excluding the transient demand from Covid stockpiling, the management said that the new take up is weaker and occupancy could trend down in the near future. 

3. Acquisitions and AEIs, while delayed, continue to be on the cards

It should come as no surprise that AREIT is reporting delays in the estimated completion dates for its AEIs and redevelopments due to the outbreak at the foreign worker dormitories. Nonetheless, asset enhancement plans continue to be on track and AREIT also announced 3 new AEIs (2 in Australia 1 in Singapore). 

There were also questions on potential acquisitions from the sponsor in Singapore and also overseas. Due to the sensitive nature of such transactions, management could only give very broad motherhood statements; they continue to be interested and have conversations with the sponsor and are doing what they can to unlock opportunities. Deals are coming back and it seems like we may see an overseas one before anything local; anyway, AREIT already did 25% of Galaxis earlier this year.

In terms of strategy, AREIT maintains that it would focus on sectors that drive economic growth like tech and bio-med. In the UK they continue to like logistics and business parks. They also continue to monitor opportunities in data centres. AREIT has a sizeable exposure to data centres from an absolute GFA perspective, however it does not pop out as much due to AREIT's size. Singtel (one of their top 10 tenants) leases data centre space from AREIT. From a pricing standpoint, the management highlighted that lower interest costs also improved the holding power of sellers and hence AREIT is not really seeing any 'Covid-pricing' yet. 

AREIT AEIs in progress (Source: AREIT)

4. DPU decline despite no retention and outlook

One analyst asked about a decline in DPU to around 3.6cts per qtr vs 4.0cts per quarter in 2019. This appeared odd given that AREIT did not retain any income and that the US acquisition in 2019 was supposed to be DPU accretive (+0.7%). To this question, the management highlighted that there were certain one-off distributions in 2019 like the rollover adjustment that contributed to about 0.25cts of distribution. 2020 results also had to account for rental reliefs given to tenants due to Covid-19 and also declines in occupancies leading to lower operational results. 

Looking ahead, one area that AREIT is poised to reap some savings is on interest cost. AREIT has some perps coming up on their reset date and whichever option it chooses to take (reset, refinance, issue bonds), AREIT is confident that there will be interest cost savings. Apart from this, most of the outlook really depends on how the Covid-19 virus progresses. 

In comparison to its Capitaland peers, AREIT has outperformed and even hit above $3.50 last week. Due to this, and the fall-off of CMT, AREIT remains the largest and most liquid REIT in Singapore. Trading at ~1.6x P/B and 4.3% FY20F yield, AREIT is in a good position to continue its growth via acquisition strategy. On the flip side, its size also means that acquisitions won't really move the needle much and AREIT does have to make portfolio-size acquisitions to continue its growth trajectory. 

Share
Tweet
Pin
Share
No comments
Frasers Logistics & Commercial Trust (FLCT) announced its 3QFY21 business update last evening. This is the first set of 'results' announced after the completion of the merger between FLT and FCOT. Due to the larger entity and mix, most of the yoy comparisons are not that meaningful since all show a huge increase due to the merger. To better assess how FLCT performed, we have to zoom into the details

1. Positive reversions for commercial but negative for industrial
During the quarter FLCT completed 134,669 sqm of leasing deals in total and achieved +10.6%/-3.9% reversions for its commercial and industrial segments respectively. The rental reversions are calculated as the new gross signing rent divided by the old terminating gross rent. 

I believe that the +12.1% reversions experienced for the 10 leases in Singapore could reflect the lower signing rents that were achieved 3-5 years ago just as the office cycle was picking up. Nonetheless, it is a commendable result especially during the Apr-Jun period which was right in the eye of the Covid-19 storm. 

For industrial rents, the negative reversions could be due to the annual increments from the previous lease being higher than the average market rental growth. Hence any reversions back to market would be a negative one. This was previously the reason cited for the negative reversions for Australian logistics properties by the FLT management. Although we prefer a positive number, I believe that the slight negative is outweighed by the longer lease terms and annual increments that are in-built into these industrial leases vis-a-vis commercial leases with little/no increments.
Leasing update (Source: FLCT)

2. Occupancies inched down but upcoming expiries low
Portfolio occupancy was 97.2%, which was held up by the strong performance of logistics (99.8%). On the commercial side, only 1 out of 6 properties registered an increase in occupancy. The weaker occupancy is largely expected due to the Covid-19 situation with tenants probably rationalizing their space requirements. Looking ahead, investors can take comfort that upcoming expiries are low (<10% in the next FY). 
FLCT Lease Expiry Profile (Source: FLCT)

3. Capital recycling amidst the pandemic
FCLT also announced the acquisition and divestment of properties following the quarter-end. It would be divesting its remaining 50% stake in its Cold Storage Facility for S$152.5m and acquiring 2 properties (logistics in Melbourne and business park in the UK) for S$89.9m. The new properties have a WALE of 4.9 and 6.7 years respectively and are both 100% occupied.

As the management mentioned that the transactions are expected to be accretive, I believe that the exit yield on the divestment is lower than that of the purchase yield on the acquisitions. 

Summary
Overall, FLCT produced a commendable set of results and continues to undertake transactions even during the pandemic. I like that the management has consistently executed 2-3 transactions every year to grow the REIT and also like the stability of the overseas logistics/industrial assets with their long leases and annual step-ups. However, one thing to note is that FLT previously experienced share price underperformance in 2018/2019 due to its FX exposure since all its assets were non-Singapore before the merger. Therefore, investors should be comfortable with the FX risk on the AUD, EUR and to some extent, the GBP. 
Share
Tweet
Pin
Share
1 comments
Singapore Airlines (SIA) released its 1QFY21 results this evening. SIA reported a 99.5% decline in passenger volumes which led to the headline $1bn net loss. While passenger volumes across its different segments fell by >99%, cargo performed better with a 55% fall in cargo and mail carried. Quite interesting to have your volumes decline by >50% but still be the best performing segment. This goes to show how bad things are for the airline industry. 


Outlook
In its outlook statement, SIA mentioned that the recovery in international air travel is slower than expected and industry experts have continued to revise their projections downward. A full recovery could take 2-4 years according to industry forecasts. For SIA, its own forecasts are that passenger capacity would not reach 50% of pre-Covid levels by the end of FY21 (Mar 2021) and will continue to re-assess its fleet size and network. For the end of 2QFY21, SIA projects that its passenger capacity would be c.7% of pre-Covid levels, a >7x jump from the current levels of <1% of pre-Covid. 

SIA appears more positive on cargo recovery as the reopening of economies and manufacturing plants could imply a greater need for air freight. It is also looking to deploy cargo-only passenger flights when justified. SIA currently has 7 freighters and 33 passenger aircraft that are deployed on cargo-only services. 

When the recovery comes possibly in 2022, SIA will also have to bear the extra maintenance costs of getting their parked aircraft back to air-worthy shape. It currently has 119 aircraft parked at Changi Airport and 29 in Alice Springs. I also do hope that by 2022, most of SIA's high fuel hedges have worn off and SIA can start getting better margins. 

On the bright side, SIA has raised $8.8bn from the rights issue and secured other lines of financing worth c.$2.2bn since Mar20 and this could put it in a better shape vis-a-vis competitors who may not have the backing of a strong parent. We have also seen other airlines like AirAsia having going concern issues and this could be a slight positive when the recovery does come for surviving airlines. 

Overall, I believe that this set of results is more negative than expected and could lead to a further softening of SIA share price. 
Share
Tweet
Pin
Share
No comments
Ascott announced its results earlier today and it wasn't pretty. Ascott had earlier set out profit guidance that distributable income could drop between 55-65% and DPU could decline by 65-75% for 1H2020. Looking at the actual results, the guidance was fairly accurate as DI declined by 56% while DPU dropped by 69%. 

I believe the decline would have been even worse if Ascott had compared it on a same-store basis since there was the merger between Ascott and Ascendas Hospitality that would have boosted the distributable income. During 1H2020, 21 of Ascott's properties were temporarily closed due to the pandemic. Since then, 12 properties have reopened and 7 more are scheduled to reopen in 3Q20. 

Operationally, we also saw the benefit of having master leases or management contracts with minimum rents. From a gross profit standpoint, management contracts experienced the worst decline of -61% while master leases actually grew 51%, although partially contributed by the Ascendas merger. 
Ascott financial performance of various segments (Source: Ascott)

Ascott has further highlighted that it has a highly diversified set of revenue streams from a geographical perspective and this could help with the recovery. As mentioned in a previous article, exposure to non-Singapore countries allows Ascott to ride on the push for domestic tourism compared to its SG-focused peers. The higher APAC exposure also allows it to ride on the strong response to Covid that APAC countries have had relative to Europe and the US. 
Ascott gross profit contribution by country (Source: Ascott)

I expect Ascott's hotel-focused peers to be even worse off as serviced residences tend to have a more stable occupancy due to longer stays. Additionally, in its largest country, Japan, Ascott actually has residential properties that it is renting out, which provides further stability to income. 

At its current price of 90cents, Ascott provides an annualized yield of 2.3% (taking 1.05Scts multiplied by 2). In reality, the yield could be around 2.5% assuming Ascott pays out the amounts retained. At such low yields, I do not believe that investing in Ascott shares provide good risk-return ratio. In fact, investing in their perpetuals might be a better choice since it has seniority over common shares and provides a higher yield at 3.07%. 
Share
Tweet
Pin
Share
No comments
Newer Posts
Older Posts

Popular Posts

  • MSCI Singapore Index rebalancing impact on stocks
  • Office REITs results round up: WFH a boon or bane?
  • 3 key concerns REIT investors should take note of

Tags

  • Centurion Corp
  • Consumer
  • Covid-19
  • Coworking
  • Eagle Hospitality Trust
  • Gloves
  • Healthcare
  • Index
  • Property
  • REITs
  • Sembcorp
  • SPH REIT
  • Supermarket

Blog Archive

  • ▼  2021 (3)
    • ▼  6 Jun - 13 Jun (1)
      • ARA Logos Logistics Trust: 3 reasons to drive a re...
    • ►  21 Feb - 28 Feb (1)
    • ►  24 Jan - 31 Jan (1)
  • ►  2020 (43)
    • ►  30 Aug - 6 Sep (1)
    • ►  23 Aug - 30 Aug (1)
    • ►  9 Aug - 16 Aug (1)
    • ►  2 Aug - 9 Aug (2)
    • ►  26 Jul - 2 Aug (2)
    • ►  19 Jul - 26 Jul (2)
    • ►  12 Jul - 19 Jul (2)
    • ►  28 Jun - 5 Jul (2)
    • ►  21 Jun - 28 Jun (2)
    • ►  14 Jun - 21 Jun (2)
    • ►  7 Jun - 14 Jun (2)
    • ►  31 May - 7 Jun (1)
    • ►  24 May - 31 May (3)
    • ►  17 May - 24 May (1)
    • ►  10 May - 17 May (3)
    • ►  3 May - 10 May (2)
    • ►  26 Apr - 3 May (3)
    • ►  19 Apr - 26 Apr (1)
    • ►  12 Apr - 19 Apr (2)
    • ►  5 Apr - 12 Apr (2)
    • ►  29 Mar - 5 Apr (2)
    • ►  22 Mar - 29 Mar (2)
    • ►  15 Mar - 22 Mar (2)

Created with by ThemeXpose